Our monthly To the Point column by economist Dr Roelof Botha offers in-depth analysis and commentary on the latest economic trends, market developments, and financial news. Designed to keep you informed and ahead of the curve, each edition delves into key economic indicators, explores their impact on global and local markets, and provides insights to help you navigate the ever-changing economic landscape.
Mini-budget well received
This year’s Medium-Term Budget Policy Statement (MTBPS), also referred to as the “mini-budget”, attracted more attention than usual, primarily due to speculation over fiscal measures to provide fuel price relief.
The National Treasury did not disappoint, with a substantial reduction in the fuel levies for both diesel and petrol having been announced for the last two months of the year, at an estimated fiscal cost of R10 billion. Fortunately, a similar amount that was previously transferred to the Central Energy Fund will take care of this foregone revenue from the fuel levy.
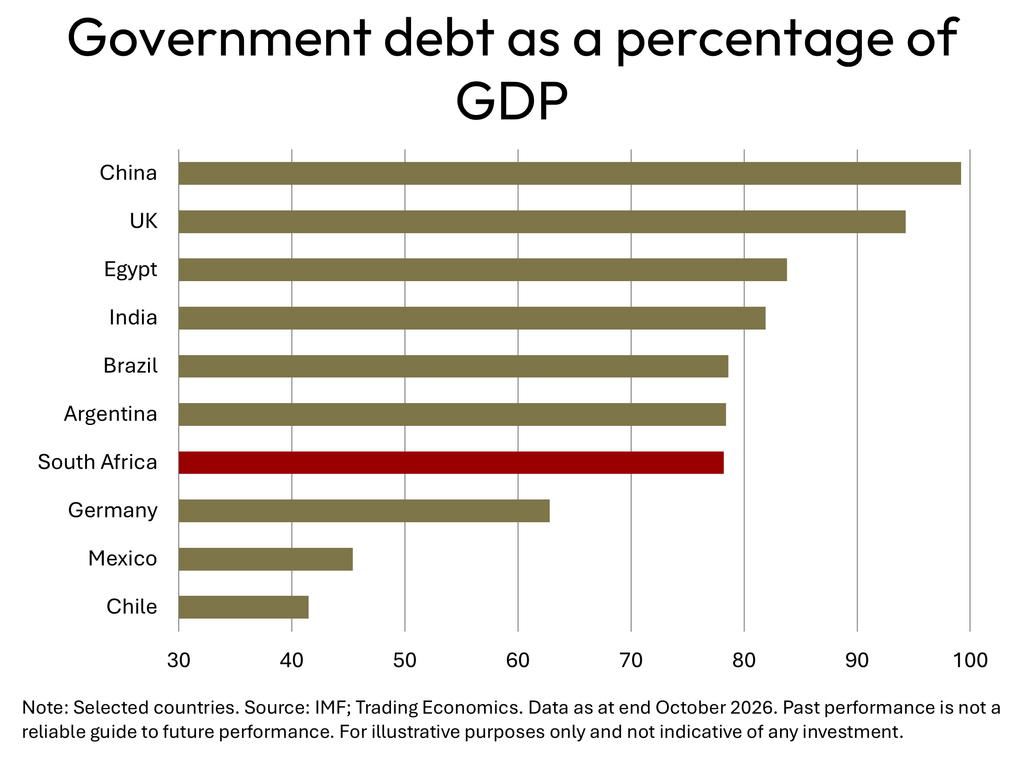
More good news was also announced, especially with regard to the outlook for taxation revenue, which has been revised upwards by R17.1-billion compared with the February estimate. Also, South Africa’s debt-to-GDP ratio has stabilised for the first time in nearly two decades and is expected to decline marginally to 78.2% during the current fiscal year. This level compares favourably to those of key trading partners and peer group countries, as illustrated by the figure.
A major milestone that was singled out in the reading of the mini-budget was the imminent implementation of the amended Municipal Public/Private Partnership Regulations, which are expected to simplify processes, reduce transaction costs and make it easier for municipalities to partner with the private sector to deliver infrastructure and services.
One of the few downsides of the mini-budget was the acknowledgement that the prolonged conflict in the Middle East and the El Niño drought had contributed to a lower economic growth forecast, namely from 1.6% in February to 1.2%.
Household finances improve in Q2
During the second quarter of 2026, the Altron FinTech Household Resilience Index (AFHRI) recorded its ninth successive increase in the seasonally adjusted value, with year-on-year growth of 2.2% – considerably higher than the comparable growth rate of only 0.9% for the country’s GDP.
Compared to the first quarter of 2026, however, the AFHRI increased by less than one percent, mainly due to declines in a number of indicators that carry a large weighting in the composite index, namely public sector salaries & employment, whilst growth in private sector salaries & employment was lethargic at below one per cent.
Over the past six years, three extraordinary circumstances have placed the financial resilience of households under pressure. The first was the lockdowns imposed during the Covid-19 pandemic, followed two years later by Russia’s military invasion of Ukraine, which led to a spike in oil prices and higher inflation. Then, between 2023 and 2024, the cost of credit and of capital rose to the highest levels in 15 years, due to a restrictive monetary policy stance.
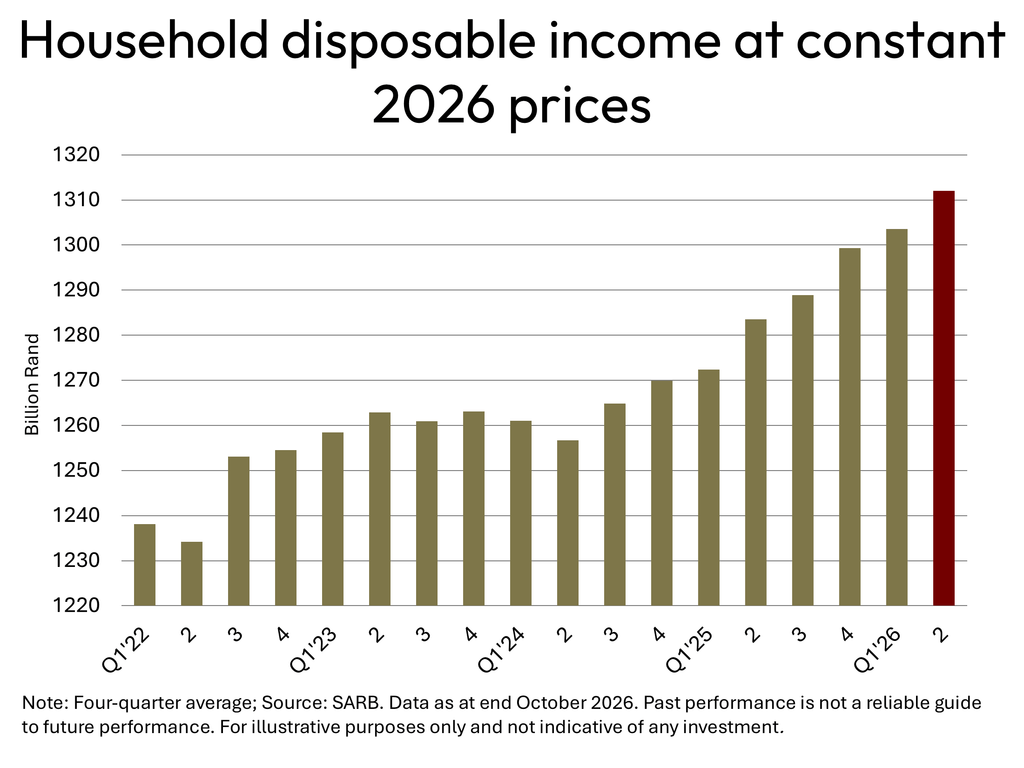
As illustrated by the figure, the rate-cutting cycle that started in September 2024 immediately lowered the debt servicing costs of households, releasing pent-up demand that has now resulted in the eighth successive quarterly increase in the real disposable incomes of households. The latter indicator is one of 20 different gauges of household financial resilience that is captured by the Altron Fintech Index. Hopefully, inflation will remain low enough to prevent another interest rate increase at a time when the economy is under-performing, and households and businesses alike are feeling the pressure of record high fuel prices.
Trade surplus marches onwards
Over the past decade, South Africa’s international trade balance has stood as a bulwark against many trials and tribulations facing the economy. Not even the last throes of state capture, nor in the aftermath of the health pandemic or the oil price spikes of 2022 and 2026 has the country’s trade balance wilted.
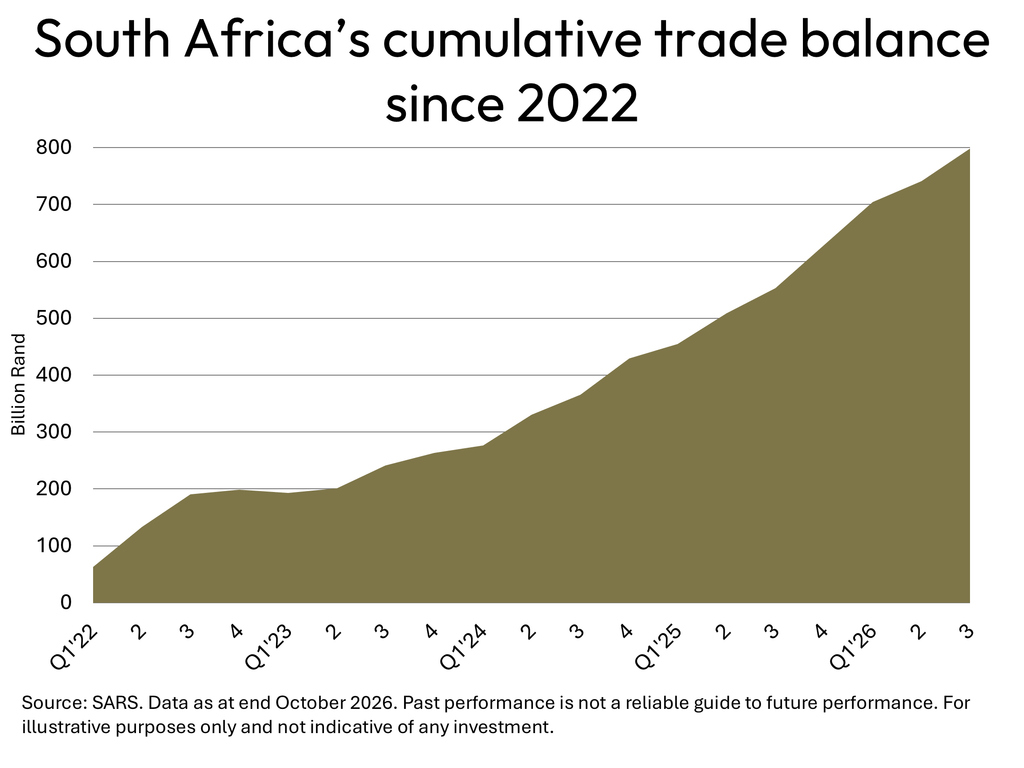
Instead, the cumulative trade surplus has just kept on growing, thereby providing fundamental support to the rand exchange rate and ensuring that imports of machinery and equipment and of intermediate goods required by manufacturers do not become prohibitively expensive.
Since 2022, the cumulative trade surplus has climbed relentlessly to reach a level of R800 billion at the end of September 2026, which also represented the 20th successive month that merchandise exports exceeded the value of imported goods.
Scrutiny of the key trade sections provides evidence of the key role played by the mining sector in creating the fiscal leeway announced by the Minister of Finance during the October “mini budget”. The bulk of the country’s minerals and precious metals is exported, and a combination of healthy volumes and sufficiently high prices has made a major contribution to an estimated revenue overrun for the 2026/27 fiscal year of more than R17 billion. Hence the affordability for National Treasury’s fuel levy reductions in November and December. Our exporters deserve a toast!
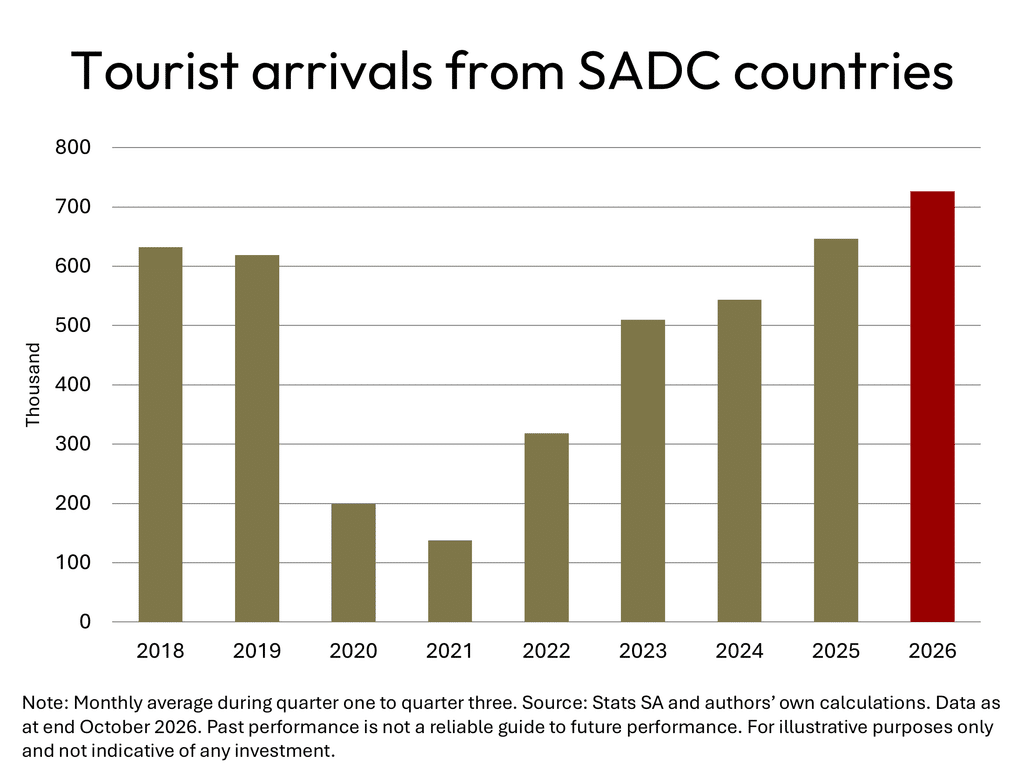
SADC tourists save the day!
Although the number of overseas travellers to South Africa continued to climb during the third quarter of 2026, the growth momentum stalled during September. Fortunately for the tourism industry at large, however, visitors from other SADC countries continue to arrive in droves and have climbed to new record highs.
During the first nine months of 2026, more than 6.5 million tourists from SADC countries visited South Africa, with Mozambique having overtaken Zimbabwe as the leading source of visitors from Africa in September. The visitors from SADC countries often stay for a single day only, with an average spend of R5,400 (as estimated by Statistics SA). This translates into an amount of R35.3 billion that accrued mainly to the sectors for retail, hospitality and transport – an increase of R3.8 billion over the figure for 2025.
South Africa is not alone in the challenging environment that currently exists for global tourism. According to data by UN Tourism, international tourism experienced a decline during the second quarter of 2026, whilst the International Air Transport Association (IATA) has reported a further drop in air travel demand during the third quarter of the year.
The reasons behind the cooling down of international tourism are mainly related to the hostilities in Eastern Europe and the Middle East, which have wreaked havoc with fuel costs, whilst also elevating the perceived risk of flying over war-torn regions. Higher global inflation and subdued economic growth in Europe have also prevented the global tourism industry to match the stellar performance of 2025, when its economic contribution increased by 4.1%.